 713-530-0575
 amir@pointcapitalservices.com
If you have built equity in your home, you may have more financing options than you realize. Homeowners commonly consider a HELOC, home equity loan, or cash-out refinance when they want to access some of the equity they have built.
But these options work differently.
A HELOC gives you a revolving line of credit that you can draw from as needed. A home equity loan generally provides a lump sum, while a cash-out refinance replaces your existing mortgage with a new mortgage and allows you to take part of your available equity in cash.
The right choice depends on your current mortgage, the amount of equity you have, your financial goals, and your ability to manage the new payment.
At Point Capital Services, we help homeowners explore available financing options and compare solutions based on their individual circumstances.
What Is Home Equity?
Home equity is the difference between your home’s current value and the amount you owe on your mortgage.
For example, if your home is worth $600,000 and your current mortgage balance is $350,000, you have approximately $250,000 in equity before considering other factors.
That equity may potentially be used as part of a financing strategy, subject to lender requirements, property value, credit profile, income, and other qualifications.
What Is a HELOC?
A Home Equity Line of Credit (HELOC) is a revolving line of credit secured by your home.
Instead of receiving one large lump sum, you generally have access to a credit line and can draw funds during the designated draw period.
This can make a HELOC useful when you don’t know exactly how much money you’ll need or when expenses will occur over time.
For example, a homeowner may consider a HELOC for:
- Home improvements
- Remodeling projects
- Large planned expenses
- Debt consolidation
- Other qualified financial needs
HELOCs commonly have variable interest rates, meaning the payment can change as the rate changes. The structure also typically includes a draw period followed by a repayment period.
Advantages of a HELOC
- Access to funds as needed
- The ability to borrow multiple times during the draw period
- Interest charged based on the amount borrowed rather than the full credit limit
- An option for homeowners who don’t need one large lump sum
However, homeowners should also understand the risks. A HELOC is secured by your home, and payments can change when the interest rate changes.
What Is a Home Equity Loan?
A home equity loan allows you to borrow against your home’s equity and generally receive the funds as a lump sum.
Unlike a HELOC, you’re typically borrowing a specific amount upfront and making scheduled payments according to the loan terms.
A home equity loan may make sense when you know exactly how much money you need for a particular project or expense.
For example, you might consider one for:
- A major home renovation
- A large one-time expense
- Debt consolidation
- Other qualified financial needs
Home equity loans commonly have fixed rates, although specific terms vary by lender and program.
What Is a Cash-Out Refinance?
A cash-out refinance replaces your existing mortgage with a new mortgage for a larger amount.
The difference between the new loan amount and your existing mortgage balance, after applicable costs and requirements, can be available to you as cash.
For example, if you currently owe $300,000 and refinance into a $400,000 mortgage, the transaction may provide access to part of that additional $100,000, subject to the loan’s terms, closing costs, maximum loan-to-value requirements, and qualification.
A cash-out refinance can be worth considering when you want to restructure your primary mortgage while accessing equity.
However, replacing an existing mortgage can have significant implications. You should compare the new interest rate, payment, closing costs, and long-term interest expense with your current loan.
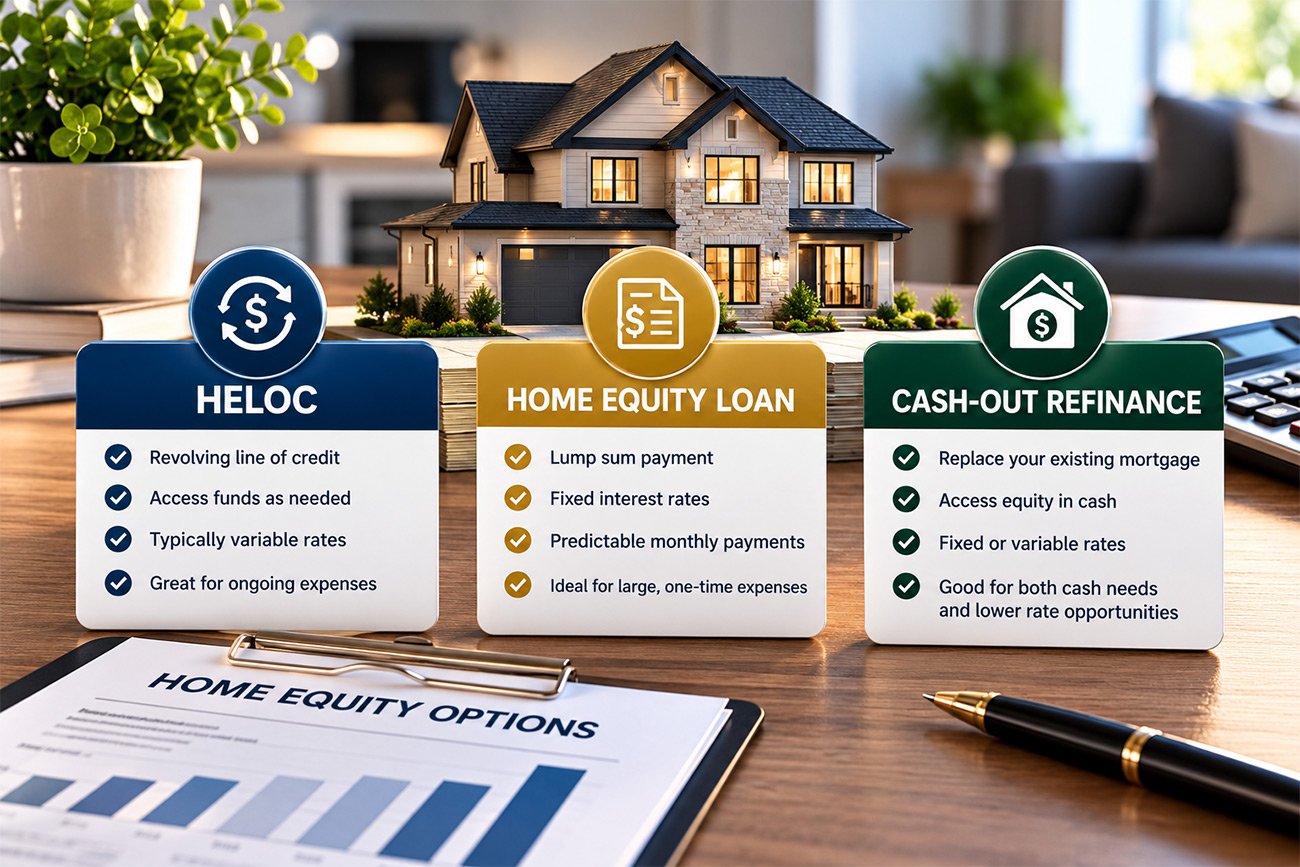
HELOC vs. Home Equity Loan vs. Cash-Out Refinance
| Feature | HELOC | Home Equity Loan | Cash-Out Refinance |
|---|---|---|---|
| How you receive funds | Draw as needed | Lump sum | Cash from refinance |
| Existing first mortgage | Usually stays in place | Usually stays in place | Replaced |
| Interest rate | Typically variable | Often fixed | Fixed or variable, depending on program |
| Best suited for | Flexible access | Known amount | Restructuring mortgage + accessing equity |
| Payment | Can change | Generally predictable | Based on new mortgage |
| Uses home as collateral | Yes | Yes | Yes |
The actual terms, rates, costs, and qualification requirements depend on the lender and loan program.
Which Option Is Better for You?
There isn’t one answer that works for every homeowner.
A HELOC may be worth considering if you want flexible access to funds rather than borrowing one large amount upfront.
A home equity loan may be worth considering if you know how much you want to borrow and prefer a lump-sum structure.
A cash-out refinance may be worth considering if accessing equity and restructuring your existing mortgage both make sense for your financial situation.
The CFPB recommends comparing the costs, risks, and terms of different options rather than focusing only on the monthly payment.
Before You Access Your Home Equity
How much equity do you have? Your available financing depends partly on your home’s value and existing mortgage balance.
What will the money be used for? Your intended use can help determine which financing structure makes sense.
What is your current mortgage rate? If you have a favorable existing mortgage rate, replacing it through a cash-out refinance may require careful comparison.
Can you comfortably handle the new payment? Remember that these financing options use your home as collateral.
What are the total costs? Look beyond the interest rate and monthly payment. Consider closing costs, fees, repayment terms, and potential rate changes.
Explore Your Home Equity Options
Your home equity can be a valuable financial resource, but choosing the right way to access it requires careful consideration.
At Point Capital Services, we help homeowners explore mortgage and home-equity financing options based on their goals and financial situation.
Whether you’re considering a HELOC, home equity loan, or cash-out refinance, we can help you understand your available options.
Ready to explore your home equity options?
713-530-0575
amir@pointcapitalservices.com
Amir Piyar Ali | NMLS #1767783
Point Capital Services | Company NMLS #2094446
Loan programs, terms, rates, and qualification requirements are subject to lender guidelines and borrower eligibility. This information is for educational purposes and is not a commitment to lend.